
How Waterfront Property Values Complicate Tax Assessments in Coastal Communities

Special permits for accessory dwelling units (ADUs) aren’t handed out at the building department counter. Here’s what the process looks like in Rhode Island, Massachusetts, and Connecticut, and how to avoid the mistakes that derail approvals.
What You’ll Learn
- How Rhode Island’s “full and fair cash value” standard is supposed to work
- Why waterfront and historic properties are harder to value than typical homes
- Common mistakes in mass appraisal models that inflate coastal assessments
- The deadlines and steps for appealing an assessment in Rhode Island
- What evidence moves an assessor or a review board
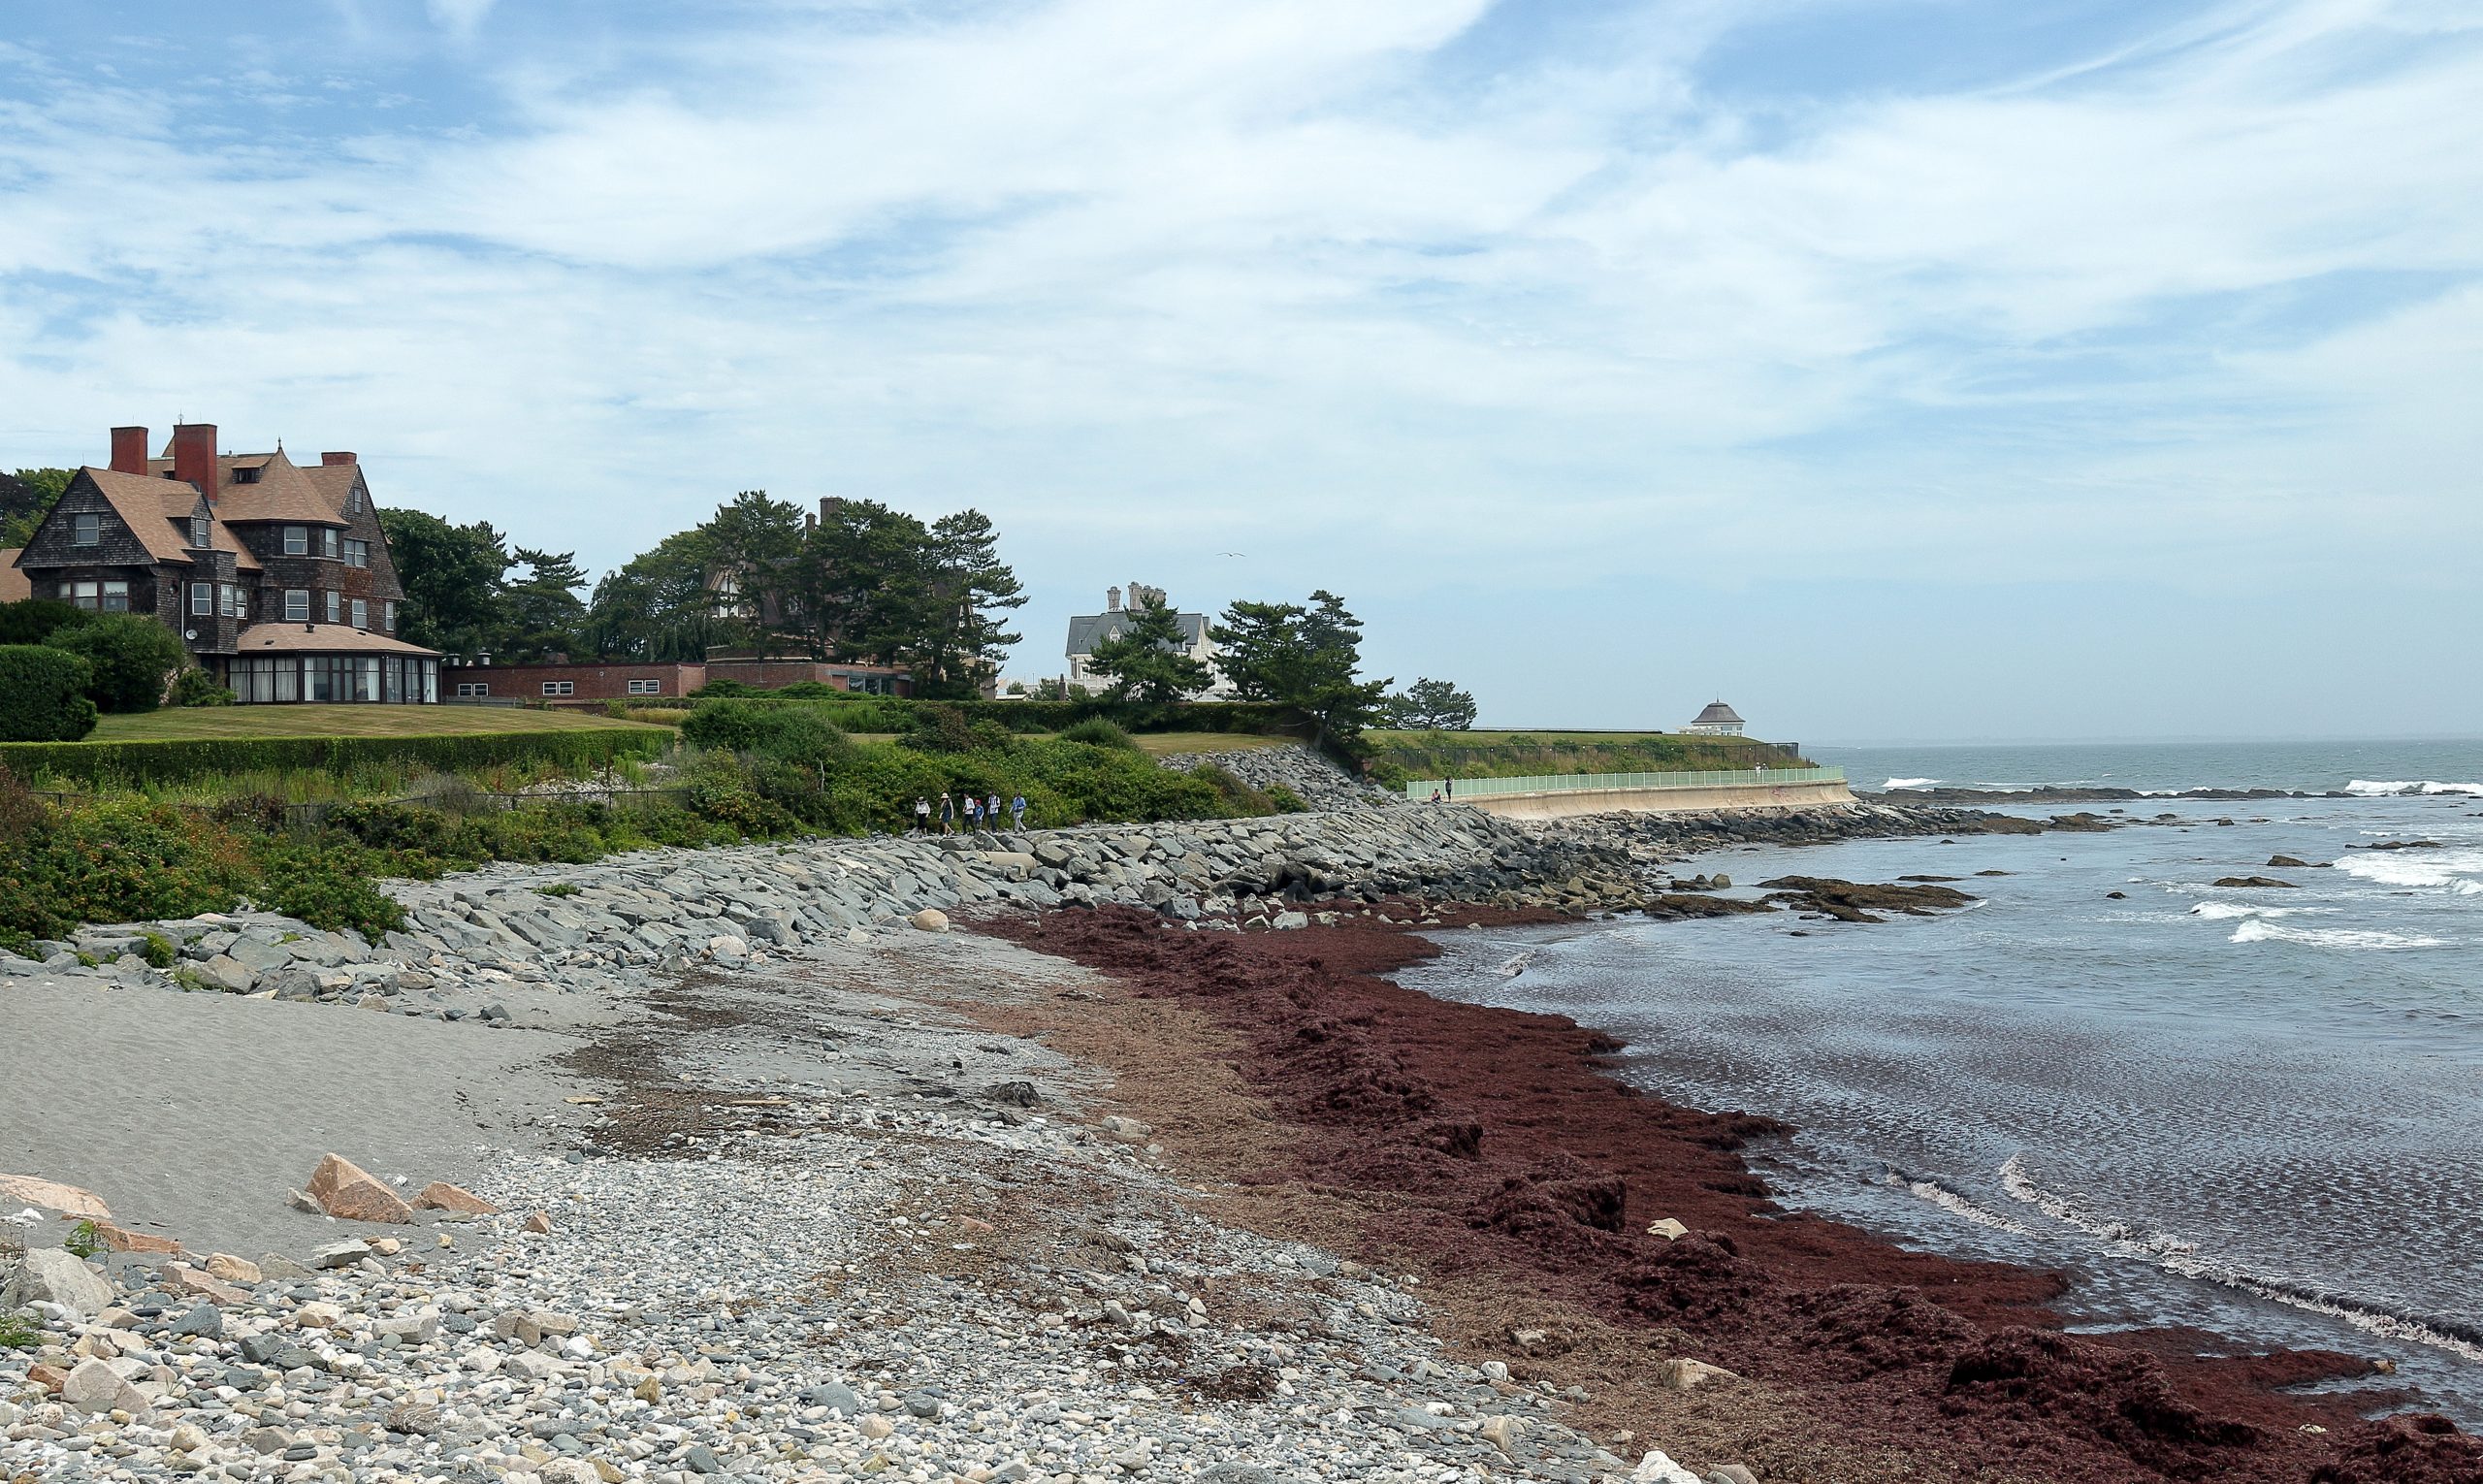
Rhode Island calls itself the Ocean State for good reason, and that shoreline is exactly why property owners in Newport, Narragansett, Jamestown, and along the rest of the coast tend to open their tax bills with more dread than most. Waterfront and historic properties don’t behave like typical residential real estate, yet many municipal assessments still treat them that way. The result is a value on paper that has little connection to what the property could sell for, and a tax bill built on that inflated number.
We’ve helped coastal property owners challenge assessments that ignored flood risk, treated a nineteenth-century cottage like new construction, or leaned on comparable sales that weren’t comparable at all. Understanding why these assessments go wrong is the first step toward getting one fixed.
The Legal Standard: Full and Fair Cash Value
Rhode Island law requires municipalities to assess real property at its “full and fair cash value,” defined under section 44-5-12 of the General Laws as the price a willing buyer would probably pay a willing seller in an arm’s-length sale on the open market. That’s the number every assessment is supposed to represent, whether the property is a triple-decker three blocks from downtown or a shingle-style cottage on the water in Watch Hill.
In practice, most Rhode Island cities and towns reach that number through mass appraisal: a computer model that sorts properties into categories, applies formulas based on recent sales, and spits out values for thousands of parcels at once. Mass appraisal works reasonably well for a neighborhood of similar homes built in the same decade. It works far less well for a property that has few true peers.
Why Waterfront Properties Break the Model
A waterfront home isn’t competing against the house two streets back from the water. Direct water access, frontage, and view all carry a premium that a mass appraisal model has to estimate, and that estimate is often based on a small number of recent waterfront sales that may not resemble the property in question. A model built around three or four comparable sales in a given year can swing wildly depending on which sales it picked up, and municipalities don’t always update those comparables as often as the market moves.
Flood risk compounds the problem. A parcel in a coastal flood zone often carries higher insurance costs, stricter building requirements, and real exposure to storm damage and erosion, all of which a rational buyer factors into their willingness to pay. Assessment models frequently miss this, especially when the underlying land value is calculated using a formula built for inland lots. We regularly see waterfront parcels assessed as though the shoreline location were pure upside, with none of the cost or risk that comes with it priced in.
Historic properties present a different set of problems. A protected or historically designated home may face restrictions on what an owner can change, from window replacement to additions, which limits what a buyer can do with the property and should, in theory, be reflected in value. Instead, these homes are often valued based on square footage and lot size, using the same formula applied to modern construction, ignoring both the cost of maintaining historic materials and the restrictions that come with the designation. An assessor’s model also has a hard time capturing deferred maintenance that’s common in older coastal homes exposed to salt air, something a real buyer would absolutely negotiate into their offer.
How to Push Back on an Inflated Assessment
The appeal process in Rhode Island runs on strict deadlines, and missing one usually means waiting until next year. An owner who wants to contest an assessment generally has ninety days from the due date of the first tax payment to file an appeal with the local tax assessor. The assessor then has forty-five days to review the appeal and issue a decision. If the owner disagrees with that outcome, the next step is an appeal to the local board of tax assessment review, filed within thirty days of the assessor’s decision. That board typically has 90 days from filing or 30 days after a hearing to rule. From there, an owner who still disagrees can appeal to superior court within thirty days of the board’s decision.
Filing the appeal is the easy part. Winning it requires evidence that addresses why the assessed value is too high, not just a general sense that the tax bill feels unfair. The strongest cases we build usually include:
An independent appraisal from someone qualified to value waterfront or historic property specifically, not a general residential appraiser unfamiliar with coastal risk factors.
Comparable sales that hold up on close inspection, meaning properties with similar water access, frontage, flood zone designation, and age, rather than the broader set of sales the municipality’s model relied on.
Documentation of flood insurance costs, flood zone maps, and any erosion or storm damage history that a buyer would factor into an offer.
For historic properties, records of the historic designation itself, any documented restrictions on renovation or use, and evidence of the added cost of maintaining historic materials.
A written explanation of any deferred maintenance or structural issues that a mass appraisal model wouldn’t have captured.
None of this needs to happen alone. Many owners get further, and get there faster, by having an attorney review the assessment methodology before the appeal is filed, since municipalities are sometimes willing to correct an obvious error informally rather than go through a full hearing.
Timing Matters as Much as the Evidence
Because the appeal window is only ninety days from the first tax due date, waiting to see if next year’s bill looks better is usually the wrong move. Assessments in Rhode Island typically get revalued on a multi-year cycle, so an inflated number from a bad revaluation can sit on the books, compounding each year, until the next citywide reassessment corrects it or an owner appeals it directly. Filing promptly, with the right evidence in hand, is the only way to fix the number now rather than years from now.
If your waterfront or historic property’s assessment doesn’t reflect what the property could sell for, Sayer, Regan & Thayer’s real estate attorneys can review the number, gather the right evidence, and walk the appeal through your town’s process.
Contact Sayer, Regan & Thayer for more information on this topic.
Sayer, Regan & Thayer is a real estate law firm serving clients throughout Rhode Island, Massachusetts, Connecticut, New Hampshire, Vermont, Maine and Florida. If you have questions about your rights as a buyer or need legal counsel during a purchase transaction, contact our office to speak with a member of our team.
This article is intended for general informational purposes and does not constitute legal advice. Boundary disputes involve specific facts and legal questions that require the advice of a licensed attorney in your state. Consult a real estate attorney before taking action.
Frequently Asked Questions
How often does my town reassess property values in Rhode Island?
Municipalities generally conduct full revaluations on a cycle set by state law, often every several years, with statistical updates in between. The exact schedule varies by city and town, so check with the local assessor’s office for the specific cycle.
Can I appeal my assessment without hiring an appraiser?
Yes, but an independent appraisal is usually the single strongest piece of evidence in a coastal or historic property appeal. Without one, an owner is often left arguing in general terms that the number feels high, which rarely persuades an assessor or review board.
Does flood zone designation automatically lower my assessment?
No. Flood zone status is a factor that a fair assessment should account for, but it doesn’t automatically reduce the value. The owner must present evidence linking the flood risk to a lower market value, such as increased insurance costs or comparable sales in similar flood zones.
What if I missed the ninety-day window to appeal?
Rhode Island’s appeal deadlines are strict, and missing the window generally means waiting until the next tax year to file. In some cases there may be other avenues, such as an abatement application for specific circumstances, so it’s worth discussing your situation with an attorney rather than assuming you have no options.
Is a historic designation likely to raise or lower my assessment?
It depends on how the assessor’s model treats it. A designation that restricts renovations and requires costly, materials-specific maintenance should, in theory, be reflected as a limiting factor on value. Many mass appraisal models don’t capture that nuance, which is exactly the kind of gap an appeal can address.